Who: Utilities, original equipment manufacturers (OEMs), aggregators, independent evaluators, and HVAC contractors in U.S. territories including New England, New York, the Upper Midwest, California and the Pacific Northwest.
What: A broader wave of grid‑interactive heat pump (GIHP) pilots has transitioned from proof‑of‑concept to operational portfolios that pair variable‑speed heat pumps with automated demand response, explicit capacity telemetry and performance‑based payments.
When: Scaling through the 2025–26 winter and into the 2026–27 planning season; figures and regulatory actions reviewed here are current through Aug 1, 2026.
Where: Dozens of utility territories — concentrated in New England and New York, expanded activity in the Upper Midwest and growing statewide pilots in California and Oregon.
Why it matters: GIHPs can deliver winter peak reduction and a new revenue stream for electrifying customers. But ROI depends on measured, market‑grade performance, workable backup‑heat controls, clear telemetry ownership and tariff design. This update focuses on the practical implications for installers, program designers and homeowners considering enrollment.
Context — what's changed since June 2026
HVAC System Guide’s review of utility filings, third‑party evaluation releases and program reports through Aug 1, 2026 finds accelerated scaling: program counts grew from roughly 50 pilots in June to more than 75 active pilots and demonstrations covering an estimated 60,000–75,000 homes and small commercial sites. That growth reflects three concurrent shifts:
- PUC and ISO pressure for market‑grade measurement & verification (M&V), making payments more performance‑linked.
- OEM firmware and API improvements that export available capacity and state‑of‑health at device or gateway level to aggregators and program administrators.
- Early regulatory decisions and ISO workstreams that permit limited capacity accreditation for aggregated GIHP portfolios in winter products—enabling some aggregator bids into ISO‑level auctions for the 2026–27 season.
New, concrete program examples
- Massachusetts and Connecticut expansions: Program administrators increased enrollments and extended pilots to multi‑family common areas and municipal buildings. The Massachusetts DPU‑mandated third‑party evaluators published preliminary spot reports in July 2026 requiring AMI‑based baselining and event caps.
- Upper Midwest aggregator model: One regional aggregator announced in July 2026 that it aggregated capacity from ~3,200 homes and successfully placed a limited bid into a seasonal capacity product, using OEM‑provided capacity telemetry and a standardized API layer.
- California statewide studies: Two IOUs in California initiated standardized telemetry pilots tied to the California PUC’s distributed energy resource (DER) proceedings; those pilots emphasize cybersecurity attestation and customer data controls as preconditions for performance payments.
What the data are showing (Aug 2026)
Independent evaluators and program reports issued in June–July 2026 indicate three consistent outcomes across diverse climates:
- Event performance: Variable‑speed residential units with device‑level available‑capacity reporting delivered average reductions between 0.9–1.6 kW per ton of rated heating capacity during dispatched events. Programs that used OEM telemetry rather than proxy metrics reported tighter dispatch reliability and narrower performance variance.
- Net energy effect: Net energy impacts have declined compared with earlier pilots. Where backup‑heat lockouts or coordinated gas/electric backup logic were enforced, net energy penalties were typically 0–1% on an annual basis. Pilots that left electric resistance backup unmanaged continued to show higher penalties (1–4%).
- Customer economics: Upfront incentives in current pilots range from $150–$1,000 depending on installation scope; recurring bill credits or capacity payments now commonly range $75–$350 per year for residential participants, with commercial and multifamily common areas earning materially higher payments tied to measured kW reductions.
Technical and business lessons — what’s new
- Telemetry as a commodity: Programs increasingly treat available capacity, runtime limits and state‑of‑health as standardized data fields. That shift reduced aggregator integration costs and dispute rates in utility payment reconciliations over the spring and early summer of 2026.
- Backup‑heat coordination remains decisive: The difference between a viable program and one with customer complaints is often whether resistance backup is locked out during events or coordinated with fuel switching. Pilots that required hardware interlocks or verified fuel‑source switching reported fewer comfort calls and better net energy outcomes.
- Market accreditation pragmatism: ISO‑NE and NYISO workstreams produced interim accreditation methods in mid‑2026 that allow conditional capacity credit for aggregated GIHP portfolios if programs meet strict M&V and availability windows. Those methods are provisional and differ regionally.
- Cybersecurity and data governance: Regulators now expect documented TLS encryption, firmware authenticity checks and explicit customer consent for telemetry sharing. California pilots, in particular, required third‑party security attestations before enrolling residential devices.
What installers and contractors should do now
Practical ROI and risk management are front and center. Recommended, concrete actions:
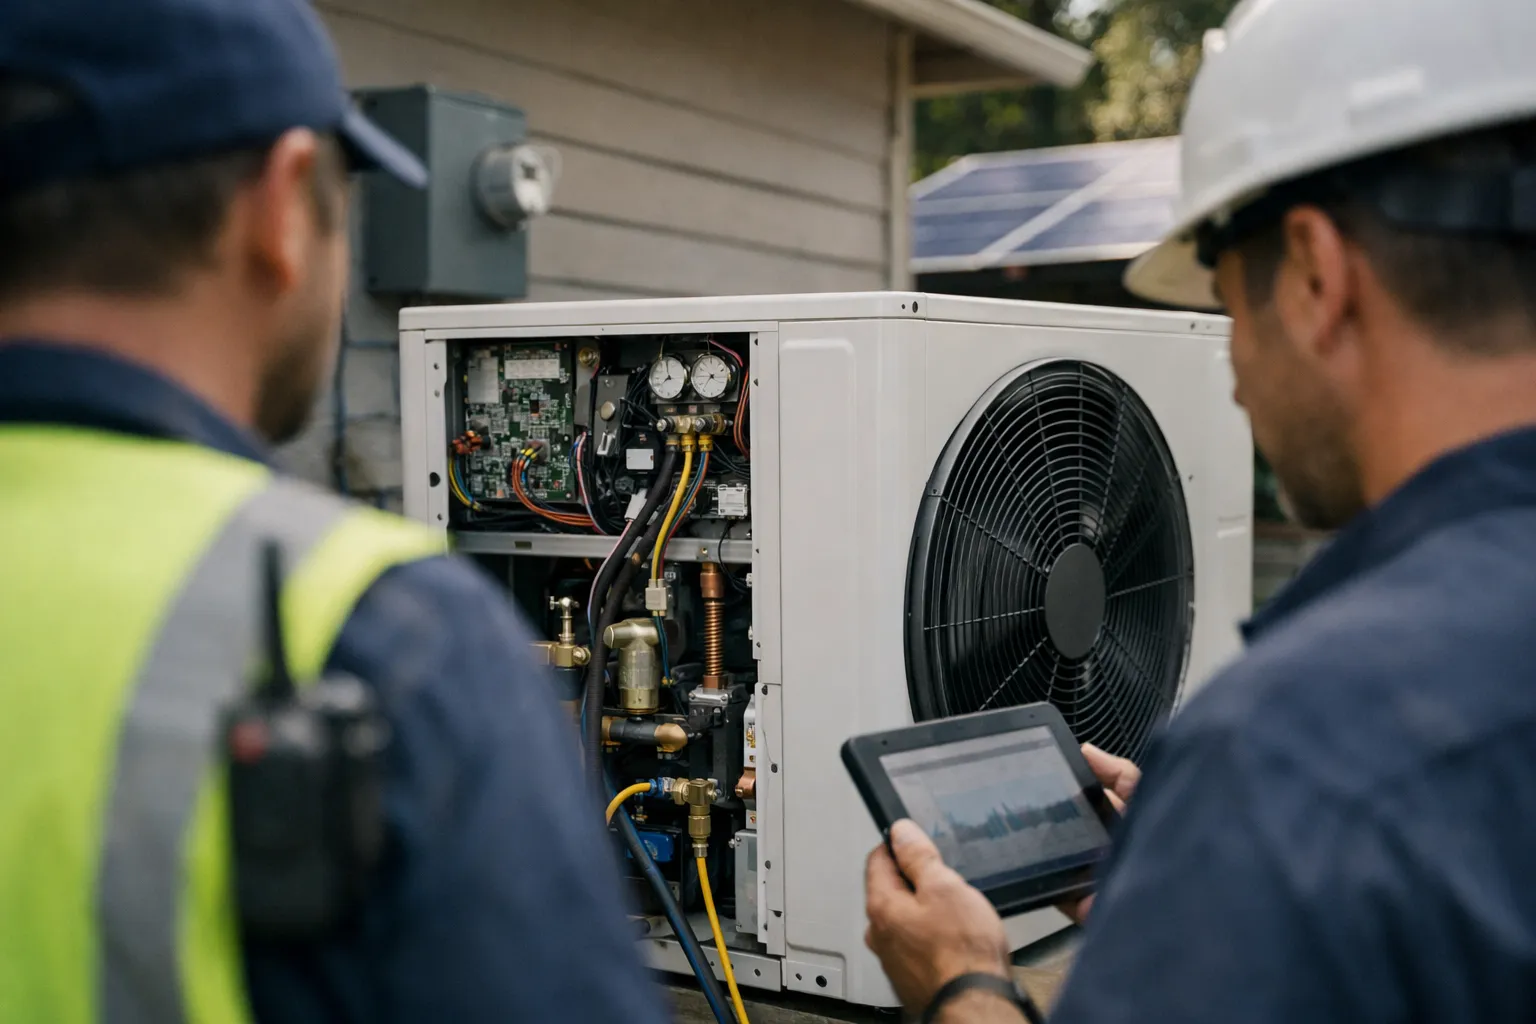
- Audit backup‑heat at install: Explicitly document backup type (electric resistance, indirect gas, fossil‑fuel boiler). If electric resistance exists, require a hardware or control interlock and test it during commissioning.
- Verify device telemetry: Insist firmware exposes available capacity, runtime limits and state‑of‑health fields to the aggregator or program gateway. Get written confirmation of telemetry schema and update policy before enrollment.
- Clarify contracts: Obtain written terms on telemetry ownership, performance payment calculation, firmware update responsibilities and warranty impacts tied to program participation.
- Set customer expectations: Provide a written ROI snapshot showing upfront incentive, expected annual credits, likely event frequency (many programs cap events at 40–100 per winter) and the potential for small temperature shifts during dispatch.
Regulatory and market shifts to watch
- State PUC decisions this fall will determine whether residential participants can be paid directly or must be compensated through an aggregator margin—expect rulings in Massachusetts and California in Q4 2026.
- ISO accreditation methodologies will be further revised before the 2027–28 capacity planning cycles; follow ISO stakeholder filings in ISO‑NE and NYISO for evolving qualification requirements.
- Standardized data schemas and a common API for available capacity could emerge from industry working groups by late 2026; this would materially reduce integration friction across OEMs and aggregators.
Impact — who benefits and who should be cautious
Beneficiaries: utilities seeking winter capacity alternatives, aggregators with robust telemetry and settlement systems, and homeowners in electrifying houses who accept modest recurring credits and occasional comfort tradeoffs.
Be cautious if: your site uses unmanaged electric resistance backup, you need immediate large cash flows (annual credits remain modest for most single‑family homes), or you lack the technical capability to document telemetry and interlocks at install time.
Reactions from the field
Utility program administrators describe cautious optimism: pilot results are "actionable" but require consistent M&V to scale payments. Aggregators report improving bid success using standardized telemetry, while contractors say demand for commissioning and cybersecurity verification is creating premium service opportunities.
What's next (near term)
- Late‑2026 independent evaluations that quantify net system value and refine net energy penalty estimates.
- PUC orders in several states clarifying consumer protections, opt‑out windows and event caps—monitor Massachusetts, New York and California filings in Q4 2026.
- Wider aggregator bids into ISO seasonal capacity auctions for the 2026–27 and 2027–28 seasons if accreditation pathways stabilize.
Practical takeaways for HVAC professionals
- Learn OpenADR basics and confirm whether your customers' program requires CTA‑2045, proprietary APIs or direct OEM telemetry.
- Document backup heat and install interlocks where needed—this is the single most common source of performance failure.
- Advise customers with a realistic ROI snapshot: show upfront incentives, likely annual credits and explain event frequency and comfort tradeoffs.
FAQ: Common questions right now
How much can a homeowner expect to earn by participating today?
Typical active pilots in mid‑2026 report upfront incentives of $150–$1,000 and recurring credits in the $75–$350 per year range for residential participants. Exact amounts depend on program design, measured peak reduction and local tariff structure. Expect higher payments for multifamily common areas and commercial sites.
Will participation increase my annual energy use?
Not necessarily. Programs that enforce backup‑heat lockouts or coordinate gas/electric backup generally avoid net energy penalties (0–1% reported in recent evaluations). If electric resistance backup is unmanaged, some pilots still show meaningful energy increases (1–4%). Confirm backup‑heat controls before enrolling.
What should installers prioritize technically?
Prioritize reliable telemetry (available capacity, runtime limits, state‑of‑health), validated backup‑heat interlocks, and written confirmation of firmware update policies. These steps protect customer comfort and ensure accurate payments.
Can aggregated heat pump capacity clear ISO markets now?
Yes, but with conditions. Interim accreditation methods in mid‑2026 allowed limited aggregated bids into seasonal winter products where programs met strict M&V and availability criteria. These accreditation rules are evolving; track ISO stakeholder filings for region‑specific requirements.
Is cybersecurity still a major concern?
Yes. Programs now commonly require encrypted communications (TLS), firmware authenticity checks, and documented customer consent for telemetry sharing. Contractors should verify security attestations before deploying endpoints.
Bottom line: GIHP pilots in Aug 2026 are moving from experiment to early operations. Measured benefits are emerging, but real ROI depends on backup‑heat management, transparent M&V, clear contracts, and installer competence in telemetry and commissioning. Consider your situation — especially backup heat type and local tariff design — before enrolling systems or offering GIHP retrofits to customers.