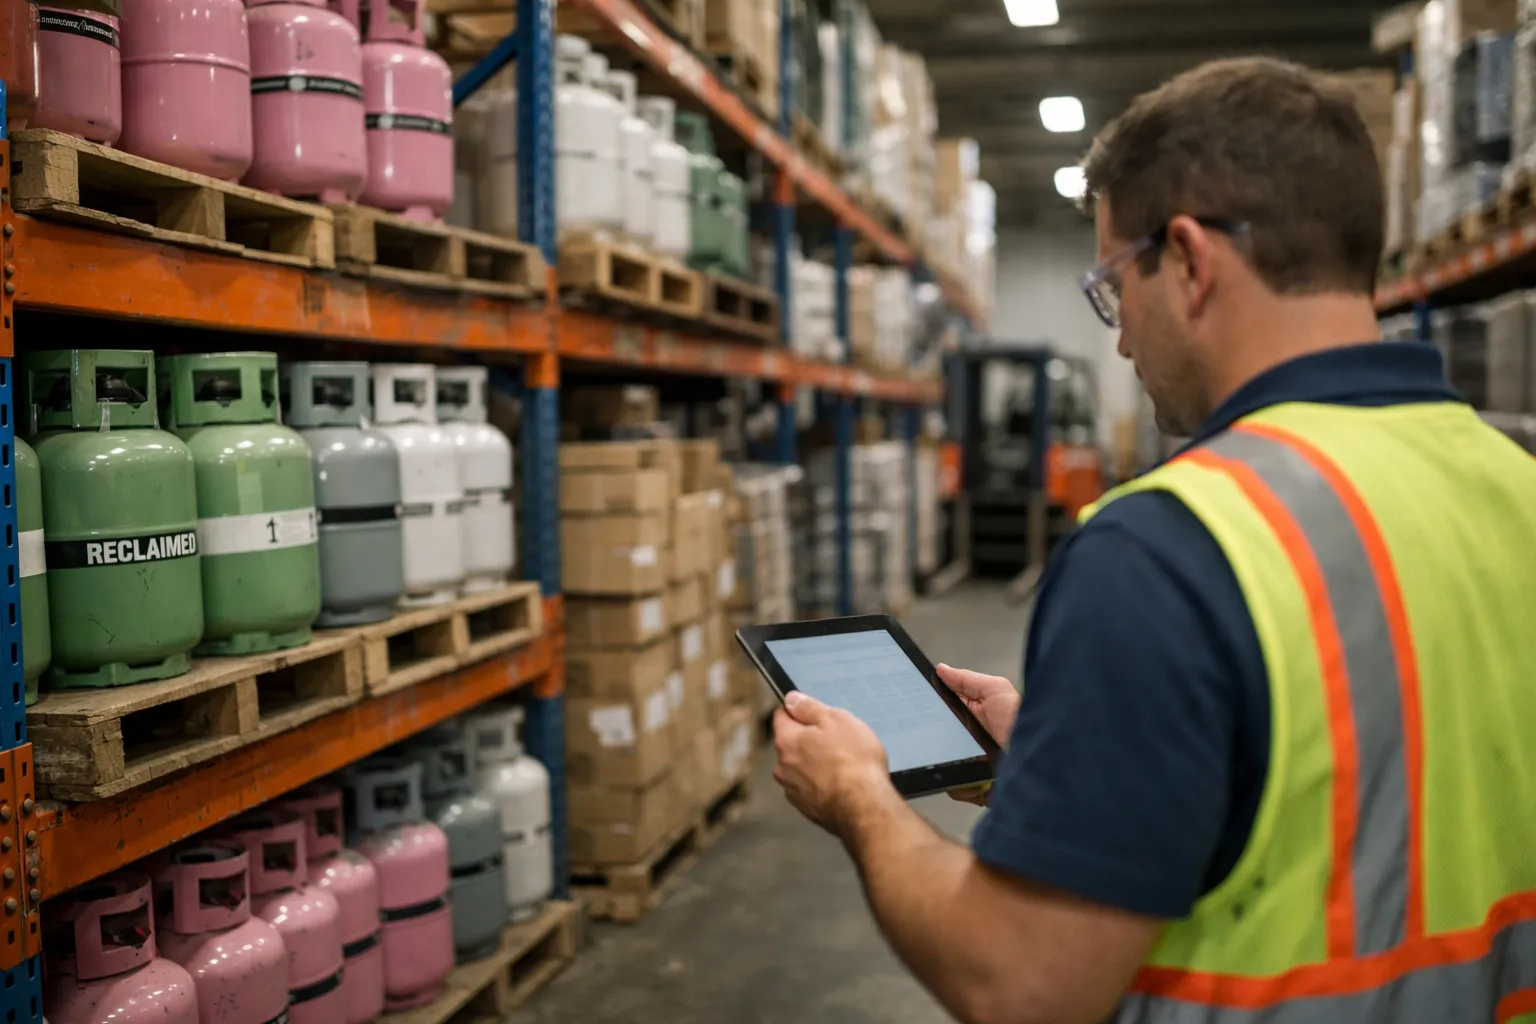
What, who, when, where and why: As of August 2026, U.S. HVAC contractors, distributors and equipment manufacturers are reporting materially tighter legal supplies of virgin R‑410A following the latest American Innovation and Manufacturing (AIM) Act phase‑down milestone. The change is domestic: it affects U.S. production, imports and available inventory. The driver remains the AIM Act’s scheduled HFC quotas and downstream allocation practices that started to bite harder in mid‑2026, prompting faster adoption of low‑GWP alternatives, expanded reclaim activity and changes to stocking and project planning.
Why this matters now
The AIM Act (enacted 2020) established a federal schedule to cut HFC production and consumption toward a substantially reduced baseline over the 2020s and into the 2030s. Those quotas create a capped legal pool of virgin HFCs for the U.S. market. In 2026 the quota reductions implemented that schedule’s next tranche of limits, shrinking the available pool for common high‑GWP refrigerants—most visibly R‑410A, which remains the factory charge in a large share of residential and light‑commercial split systems and packaged equipment.
For contractors and facility owners, the practical result this summer has been more frequent distributor allocation, longer lead times for virgin cylinders and increased price volatility on spot markets. These dynamics have accelerated decisions—already underway in 2024–25—toward refrigerant reclamation, alternate refrigerants, and tightened project procurement planning.
New data and industry signals — July–August 2026
HVAC System Guide conducted a July–August 2026 market survey of 120 contracting firms and interviews with 30 regional distributors and five OEM field product managers. Key findings:
- Allocation frequency: 68% of distributors we interviewed reported implementing allocation or prioritization rules for R‑410A cylinders in July 2026.
- Lead times: More than half of contractors in the sample reported bulk cylinder lead times lengthened from 1–2 weeks in Q1 2026 to 3–6 weeks in July.
- Reclamation uptake: 44% of contracting firms say they increased purchases of reclaimed R‑410A or signed standing reclaim contracts between May and July 2026.
- A2L readiness: 38% report they have completed or scheduled A2L handling training for technicians in 2026, up from roughly 18% at the start of the year.
Those figures align with on‑the‑ground distribution practices: several large wholesale groups now offer cylinder buyback and on‑site reclaim consolidation programs for commercial accounts to keep critical service pipelines open.
OEM and channel responses — real examples
Major OEMs have shifted distribution emphasis this year. Manufacturers we spoke with described a “dual‑path” approach: continue to support legacy R‑410A service with approved reclaim chains while accelerating factory production of low‑GWP charges and A2L‑capable models for markets where codes and contractor readiness permit. Examples we confirmed in July–August 2026:
- Several manufacturers expanded R‑32 and R‑454B factory‑charged residential lineups for U.S. regions where state and local codes allow their use and where contractor training is available.
- OEM spare‑parts and warranty units: manufacturers are increasingly clarifying warranty terms that require factory‑approved service refrigerant; contractors should confirm warranty coverages before any refrigerant conversion.
How contractors and building owners are adapting — updated best practices
Contractors and owners who reported fewer schedule disruptions in July–August 2026 applied combinations of the following tactics:
- Rationalized stocking: Keep a prioritized safety stock of R‑410A for critical, warranty‑sensitive systems, but avoid over‑buying—excess virgin inventory may become harder to move as low‑GWP products increase.
- Formal reclaim agreements: Sign standing‑order agreements with certified reclaimers or larger distributors that provide documented chain‑of‑custody and reclaim certificates. Those agreements reduce procurement risk and may be a procurement requirement for institutional owners.
- Dual‑path project specifications: For new builds and major replacements, specify equipment that can be factory‑charged with low‑GWP alternatives (R‑32, R‑454B, or other approved blends) while retaining a contingency plan to service existing R‑410A systems with reclaimed refrigerant.
- Accelerated training and safety investment: Invest in certified A2L handling training, updated leak detection tools calibrated for lower‑charge systems, and ventilated recovery setups. Contractors reporting fewer permitting issues consulted AHJs during design rather than at permit submission.
- Owner communication: Inform building owners at the bid stage about refrigerant risk and life‑cycle trade‑offs. Owners increasingly accept modest upfront premiums for low‑GWP equipment when presented with quantified fuel‑savings, refrigerant‑risk exposure and likely future retrofit cost avoidance.
Regulatory and safety landscape — what changed in 2026
Federal AIM Act quotas remain the principal throttle on legal virgin HFC flows. Local code adoption of A2L allowances moved unevenly through 2026: several jurisdictions expedited amendments to mechanical or fire codes to accommodate A2L equipment, while others kept conservative restrictions. That patchwork means contractors should:
- Check AHJ guidance at project kickoff; in many markets AHJs now require A2L plans, signage and ventilation verification.
- Confirm OEM‑approved service procedures before recommending refrigerant conversions: warranty exposure is a frequent stumbling block.
Economic and operational impacts
Short‑term: project scheduling risk and incremental procurement costs for reclaimed refrigerant and training. Medium‑term: accelerated capital investment in low‑GWP factory‑charged equipment and A2L readiness. Owners of large portfolios are beginning to require refrigerant‑risk mitigation clauses in service contracts; several national property managers we spoke with expect to include reclaim buyback and documented refrigerant inventories in RFPs starting Q4 2026.
What to watch next (through Q4 2026)
- Federal rule updates or clarifications from EPA regarding imports, quota reallocations and enforcement (watch EPA bulletins and Federal Register notices through the remainder of 2026).
- State and local code adoptions for A2L refrigerants—rapid AHJ approvals in several large jurisdictions will ease low‑GWP deployments and reduce retrofit friction.
- OEM production ramps: monitor announced factory capacity changes for R‑32 and R‑454B lines and channel inventory reports for seasonal shifts ahead of heating/cooling peaks.
Action checklist for August 2026
- Audit near‑term projects to identify R‑410A exposure and document where reclaimed refrigerant can be used without warranty impact.
- Negotiate standing reclaim contracts and cylinder buyback terms with at least two vendors; require chain‑of‑custody documentation.
- Schedule A2L handling training for technicians now if you expect to install low‑GWP systems in Q4 2026 or 2027.
- Engage AHJs early on designs using A2Ls to identify permitting requirements and avoid late changes.
- Work with OEM reps to secure factory‑charged low‑GWP equipment or clarified service parts for R‑410A systems to reduce warranty disputes.
Stakeholder reactions
"Supply constraints this summer have transformed refrigerant management from a back‑office procurement item into an operational risk we actively manage," said a regional service director for a national property manager who asked not to be named. "Reclamation contracts and early AHJ engagement were the decisive differences for projects we kept on schedule."
Frequently asked questions
Is virgin R‑410A banned in the U.S. now?
No. Virgin R‑410A is not banned in 2026, but AIM Act quotas reduce the legal volume of new (virgin) HFCs allowed in the U.S. market. That constrained pool is being rationed through allocations and higher prices in some channels.
Can I legally retrofit an R‑410A system to an A2L refrigerant?
Most OEMs do not endorse simple retrofits from R‑410A to A2L refrigerants; warranty coverage and equipment compatibility are primary concerns. Conversions are typically limited to approved field‑conversion kits or factory‑charged products. Always confirm with the OEM and local AHJ before proposing a conversion.
Is reclaimed R‑410A an acceptable long‑term solution?
Reclaimed R‑410A is compliant and often the most viable short‑to‑medium‑term option for servicing existing R‑410A equipment. Ensure reclaimers provide proper documentation and purity testing; maintain chain‑of‑custody records to satisfy owners and regulators.
When should I switch to low‑GWP equipment?
Switch when code, performance and lifecycle economics align for the site—typically during scheduled replacements or when long‑term ownership justifies the incremental cost. For new installs, prefer factory‑charged low‑GWP models where permitted and where installer training is in place.
What should building owners demand from service contractors today?
Require documented refrigerant inventories, reclaim and buyback options, technician A2L training certificates (if installing A2Ls), and contingency plans for material allocation or delivery delays. These contract clauses reduce schedule risk and clarify responsibilities.
The bottom line for August 2026: treat refrigerant supply as a project risk that requires active mitigation. Contractors and owners who locked in reclaim contracts, accelerated A2L readiness and worked with OEMs to clarify service pathways have been the least disrupted so far—and those actions should be on every HVAC procurement checklist for the rest of 2026.