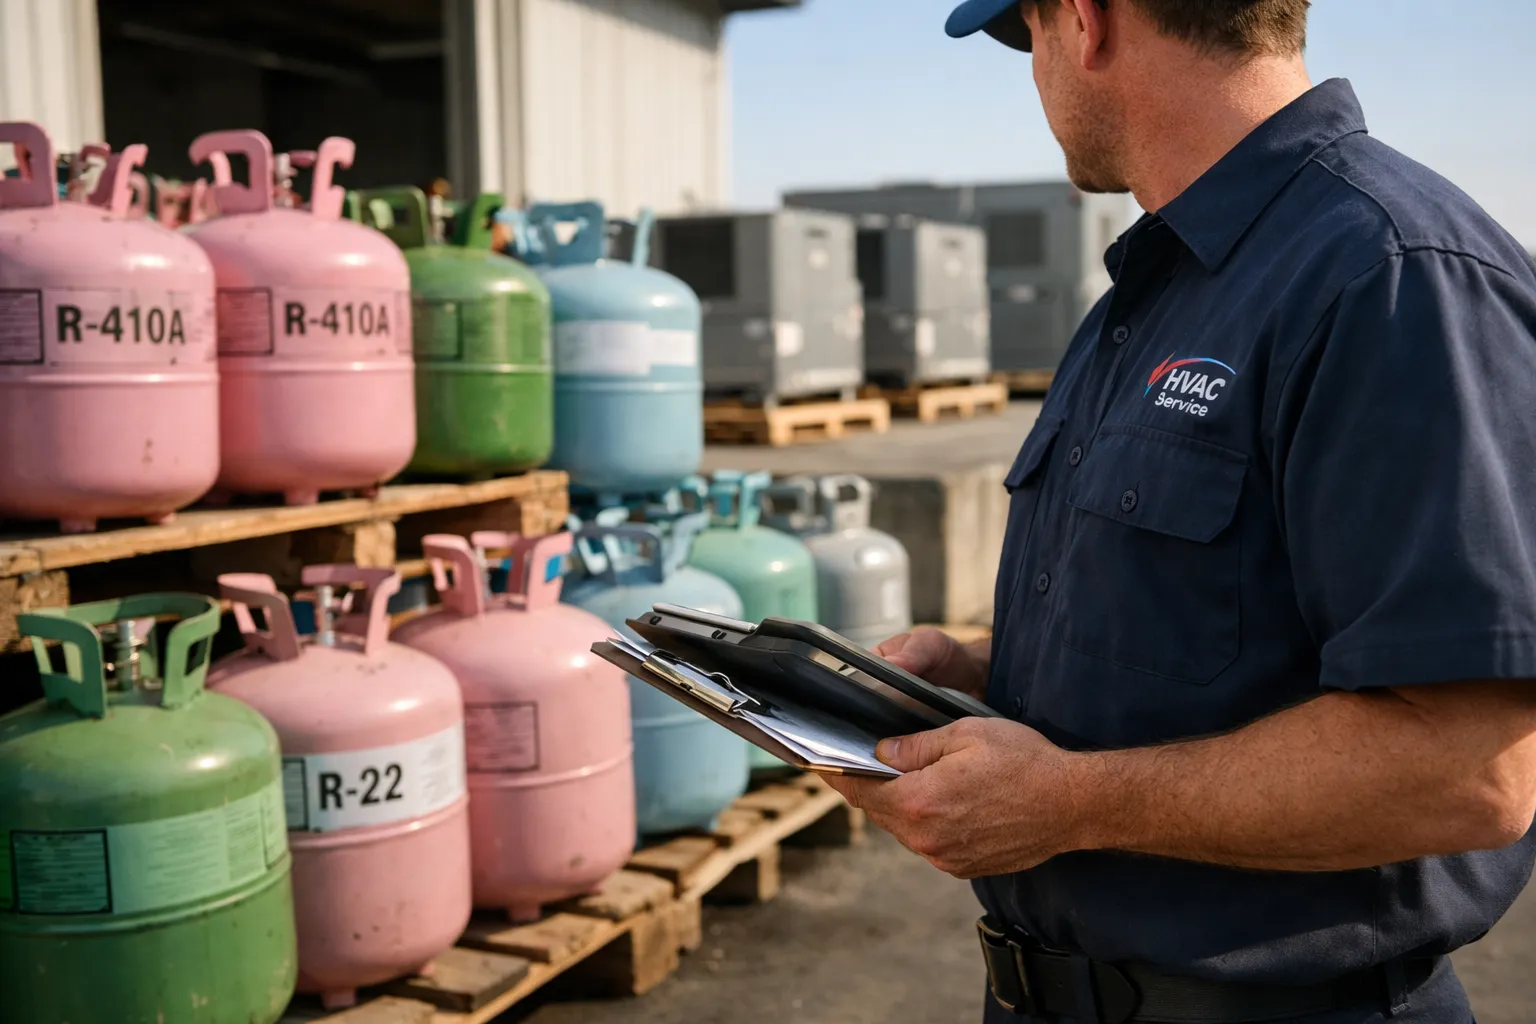
Federal action on hydrofluorocarbon (HFC) allowances for 2027 is reverberating across the HVAC industry: reduced allocations under the AIM Act have tightened spot supply of R‑410A, driven prices upward over the past month and accelerated vendor plans to pivot inventories and product roadmaps toward low‑GWP refrigerants and system designs.
What the new allowance rule does
The Environmental Protection Agency’s finalized allocation for the 2027 control period reduces available production and import allowances for HFCs as part of the AIM Act phase‑down schedule. The rule narrows the legal supply window for legacy refrigerants commonly used in residential and light‑commercial equipment, most notably blends sold as R‑410A.
Manufacturers and importers must operate within the updated allowance quantities; once allowances are fully used, production or import of those HFCs is not authorized. For contractors and distributors that rely on spot market purchases for service calls, the mechanics of allowance timing and existing inventories matter immediately.
Market reaction: R‑410A spot prices and availability
Since the rule was finalized, spot market activity has shifted. Distributors report rising bid prices for R‑410A and longer lead times for small cylinder purchases. Several national wholesalers told HVAC System Guide that spot offers have risen in recent weeks as buyers cover summer service inventories and as traders reconcile forward positions with the new allowance outlook.
For service contractors, the implications are practical and immediate:
- Higher per‑ton refrigerant cost increases the variable cost of common maintenance and recharge jobs.
- Distributors are enforcing smaller maximum purchase quantities per invoice to stretch remaining stocks.
- Some contractors are prioritizing planned replacements and retrofits that move customers toward equipment already charged with low‑GWP alternatives.
Manufacturer responses and product timelines
Major OEMs have reiterated public roadmaps to A2L (mildly flammable, low‑GWP) and HFO‑blend refrigerants, and many are accelerating production and stocking of factory‑charged systems that use these alternatives. Several manufacturers are also emphasizing factory‑sealed modular units to reduce field handling of refrigerant.
On the component side, valve, compressor and control suppliers are updating training, labeling and parts kits to support service on new refrigerant families. Field serviceability and technician safety remain central themes as the fleet mix shifts.
Regulatory and safety considerations for contractors
The allowance shift does not change safety codes overnight, but it increases the pace of transitions that require installers to be upskilled. Key considerations:
- Refrigerant procurement: Contractors should audit cylinder and drum inventories, confirm distributor allocation policies, and discuss supply plans for winter service demand.
- Training and certification: As low‑GWP refrigerants proliferate, ensure technicians have manufacturer training for A2L handling and that business liability insurance is updated for new refrigerant classes.
- System selection: OEMs are increasingly shipping systems pre‑charged and sealed; prioritizing these for retrofits reduces field refrigerant usage and simplifies compliance.
Inventory and sales strategies
Several distributor networks are already recommending that contractors shift purchase patterns: build modestly larger inventories of commonly used components and transition sales messaging toward replacement with factory‑charged low‑GWP heat pumps or packaged units. Contractors with diversified product lines will have more resilience if spot refrigerant markets tighten further in winter.
Longer‑term industry effects
The EPA’s action reinforces a structural shift that has already been underway: manufacturers are launching new product families optimized for low‑GWP refrigerants, and system architects are favoring designs that minimize on‑site refrigerant handling (e.g., hydronic heat pumps, heat‑pump water heaters, factory‑sealed ducted units and modular VRF systems with centralized charge).
Market signal effects include accelerated R&D for refrigerant‑efficient compressors and controls, and a growing aftermarket for refrigerant recovery and reclamation services. Commercial customers and property owners may see short‑term cost pressure but benefit from longer‑term device modernizations that reduce global warming potential (GWP) exposure and often improve seasonal efficiency.
What contractors should do this month
- Contact primary distributors to confirm allocation or purchase limits and get guidance on forward coverage for fall/winter service.
- Audit on‑hand refrigerant and reclaim inventory; segregate reusable reclaimed refrigerant and track chain‑of‑custody.
- Update service proposals to include refrigerant surcharge clauses that transparently pass market volatility to customers.
- Prioritize manufacturer trainings on low‑GWP refrigerant handling and A2L safety protocols; verify required PPE and leak‑detection equipment.
- Discuss product substitution pathways with sales teams to offer factory‑charged low‑GWP replacements where codes and budgets permit.
Bottom line
The EPA’s 2027 HFC allowance decision tightens a market that was already migrating away from R‑410A. For HVAC professionals, the immediate priorities are supply planning, technician readiness and customer communication. Firms that move early to align inventory, training and sales toward low‑GWP, factory‑charged solutions will reduce operational risk and position themselves for the next wave of product rollouts.