Overview
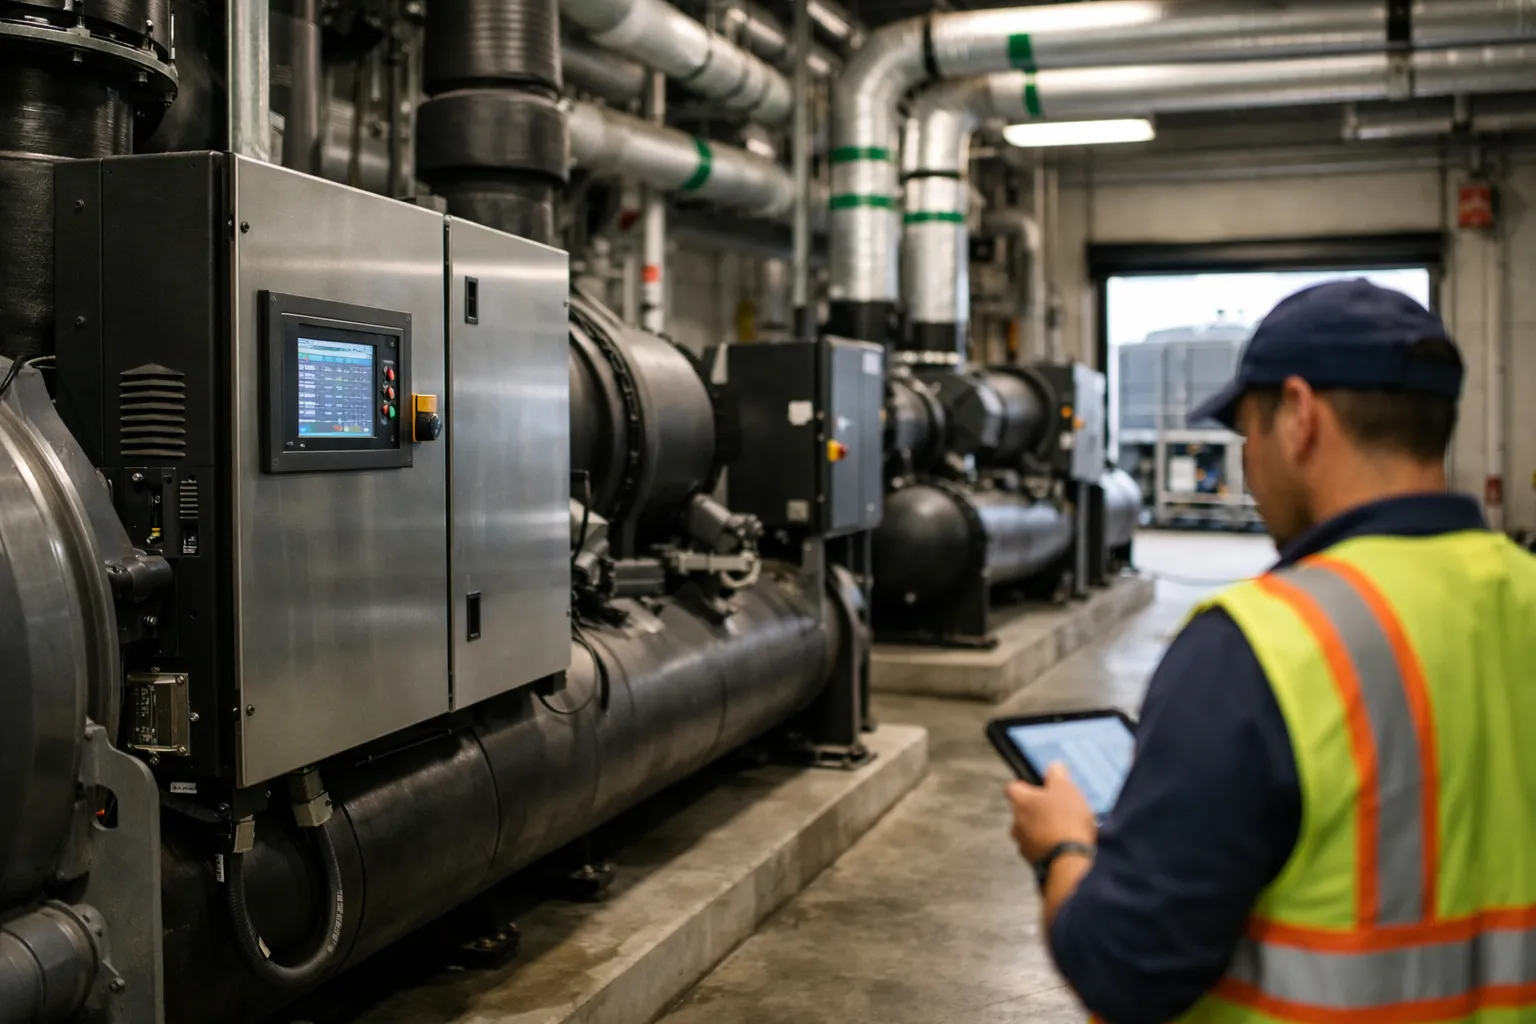
Owners, consulting engineers and specifiers choosing medium‑scale chilled‑water plants (roughly 1–5 MW) face a familiar question: inverter‑driven centrifugal chiller(s) or a modular bank of VSD screw chillers? The stakes are higher in late‑2026: tighter decarbonization targets, wider adoption of low‑GWP refrigerants, stronger grid interaction requirements, and improved inverter and bearing technologies have shifted the lifecycle tradeoffs. This update synthesizes field trends through November 2026, refreshes lifecycle economics with current assumptions, and adds practical selection and commissioning guidance you can act on now.
Background: what’s changed since mid‑2026
Since early 2022 the market moved steadily toward high part‑load efficiency and smarter controls. Through 2025–2026 several converging developments influenced buyer decisions:
- Power electronics advanced: SiC (silicon carbide) inverter modules became common in larger chillers, reducing inverter losses and thermal management needs.
- Magnetic and oil‑free bearings matured further: OEMs scaled production, lowering incremental cost and increasing field confidence in extended maintenance intervals.
- Low‑GWP refrigerants (HFO blends and low‑charge CO₂ variants) entered broader use, influencing compressor choice, heat‑exchanger design and service training.
- Grid programs expanded: demand‑response, capacity pricing, and frequency services created new operational value for variable‑speed machines able to modulate precisely.
- Service and analytics: SaaS‑based remote monitoring, digital twins and predictive maintenance packages became standard purchase options, narrowing perceived service gaps between technologies.
Data and evidence: what field performance shows in 2026
Independent lab testing, OEM field trials and energy consultancy audits through mid‑2026 indicate a few consistent findings (findings are aggregate trends; site variability remains high):
- Part‑load advantage persists, but gap narrows. In many installations inverter centrifugals still deliver the best integrated site COP at high part‑load hours, but modern VSD screw banks with optimized staging and controls close 60–80% of that gap in real plants.
- Energy value rises with electricity price and operating hours. Where annual delivered cooling exceeds ~3,000–4,000 MWh and commercial electricity prices or time‑of‑use differentials are significant, life‑cycle analyses increasingly favor inverter centrals.
- Refrigerant and thermal integration matter. Low‑GWP refrigerant options and heat‑recovery schemes change compressor thermodynamics and can tilt the balance depending on recovered‑heat value.
- Reliability data improving. Field‑service records from 2024–2026 show decreasing unplanned downtime for centrifugal units as inverter and bearing vendors standardized spares and remote diagnostics; lead times for some components also shortened with scaled manufacturing.
Illustrative 20‑year lifecycle model (updated assumptions)
This is an illustrative model to show sensitivity to contemporary inputs. Replace with site‑measured loads for decisions.
- Annual delivered cooling: 4,000 MWh
- Average operational COP (site average): inverter centrifugal = 5.8, VSD screw bank = 5.1 (reflects improved electronics and controls in both platforms)
- Electricity price: $0.15/kWh (commercial rate / TOU blended), escalator 2%/yr
- Initial installed cost: centrifugal plant 10% higher than screw bank
- Annual O&M delta: centrifugal net savings $6,000/yr (less oil handling, higher electronics service); assume warranty and service contract differences may alter this
- Analysis horizon: 20 years
Energy consumption = delivered cooling (kWh) / COP
Centrifugal: 4,000,000 kWh / 5.8 ≈ 689,655 kWh → annual energy cost ≈ $103,448
VSD screw: 4,000,000 kWh / 5.1 ≈ 784,314 kWh → annual energy cost ≈ $117,647
Annual energy savings ≈ 94,659 kWh ≈ $14,199 at $0.15/kWh. Add O&M delta $6,000 → annual benefit ≈ $20,199. If baseline installed cost ~ $1.5M, a 10% centrifugal premium (~$150k) yields payback ≈ 7–8 years. Higher local rates, value from demand‑response payments, or capturing heat recovery tighten payback further.
Takeaway: updated 2026 inputs generally shorten payback for inverter centrals versus the figures quoted in 2026’s earlier months—principally because electricity prices and the value of flexible grid services have increased and inverters/bearings have improved.
Multiple perspectives: vendors, owners and service providers
- OEMs: Major centrifugal OEMs emphasize broader product portfolios (smaller modular centrals, optional medium‑voltage drives) and bundled monitoring/warranty contracts. Screw OEMs highlight reduced first‑costs, lower local service complexity and very mature spare‑parts ecosystems.
- Owners/operators: Large energy‑intensive campuses and hospitals that can centralize maintenance favor inverter centrals for measured savings. Facilities with decentralized technical teams or strict N+1 redundancy mandates often prefer screw banks for modular fault tolerance.
- Consultants/ESCOs: Energy services firms recommend explicit valuation of ancillary grid services, heat‑recovery revenue and the cost of controls upgrades; they increasingly require digital acceptance testing and performance guarantees tied to measured site COP rather than nameplate figures.
Reliability, service and risk management — what to check in 2026
- Service contracts and spare strategies: Ask OEMs for local stocking patterns for inverter modules, bearings and low‑GWP refrigerant spares. Longer lead times exist for some specialized inverters; negotiated hot‑swap spares or rental units can mitigate risk.
- Warranty and performance guarantees: Seek measured performance guarantees (kWh/MWh or annual energy use) and penalties or rebates—these are now standard in many large projects.
- Cybersecurity and remote operations: With operator reliance on OEM SaaS telemetry, verify patching policies, network segregation and data ownership as part of the procurement process.
Retrofit and system‑level considerations
Retrofits remain a common decision point. Practical items to surface early:
- Electrical service and MV options: Some projects now prefer medium‑voltage inverter options to reduce plant‑side switchgear and cable costs—evaluate at early concept stage.
- Hydronics and delta‑T: Wide turndown capabilities require proper pump and control sequences to preserve delta‑T and avoid low‑ΔT syndrome. Digital commissioning with a temporary digital twin can reveal systemic mismatches before install.
- Refrigerant handling and codes: Local code acceptance of HFO blends and CO₂ systems varies—confirm permit timelines and technician certification requirements during early procurement.
Where each approach makes most sense in late‑2026
- Favor inverter centrifugal when:
- Plant has large sustained part‑load hours and a centralized O&M team
- Electricity costs, time‑of‑use or grid flexibility payments are material
- Owner wants to capture heat recovery or provide grid services
- Site can support electrical and rigging needs and secure service contracts
- Favor VSD screw banks when:
- Modularity, staged capital deployment or strict N+1 redundancy dominate
- Site has limited crane or service access and local technicians prefer screw platforms
- Low initial capex or phased buildout is essential
- Project timelines cannot accommodate refrigerant permitting or specialized inverter lead times
Updated practical checklist for specifiers (actionable)
- Collect high‑resolution load data (sub‑hourly, one year minimum) and include TOU and ancillary market signals in the model.
- Model lifecycle cost across scenarios: electricity price bands, value of demand‑response, refrigerant choices, and O&M contract structures.
- Require measured performance guarantees (kWh/yr or COP) with clear acceptance testing protocols and remedies.
- Validate local service network, spare part lead times and availability of warranty‑period hot spares.
- Include cybersecurity, data ownership and remote access clauses in contracts for OEM telemetry services.
- Plan for controls integration: pump sequencing, tower control and plant‑level algorithms are necessary to realize theoretical gains.
Implications
In late‑2026 the decision remains site specific, but the balance has shifted modestly toward inverter centrals when higher energy prices, grid service value and long part‑load hours exist. At the same time, screw banks retain strong value for staged projects, strict redundancy needs and constrained sites. The biggest single determinant is increasingly the quality of the control and service package rather than the compressor type alone.
Outlook: what to watch next
Over the next 12–24 months watch for:
- Further commoditization of SiC inverters and falling prices for magnetic bearing options.
- Wider utility programs paying for flexible thermal loads—if payments grow, the operational value of fine turndown increases.
- Regulatory pressure on refrigerant GWP and product certification timelines that could favor low‑charge, oil‑free designs.
- More contracts tying vendor payment to measured performance; expect increased use of digital acceptance testing and energy‑based warranties.
FAQ
Is one technology inherently more reliable than the other?
No. Reliability now depends more on OEM supply chain, local service ecosystem, and service contracts than on compressor type alone. Centrifugals rely on advanced inverters and bearings (with different failure modes); screws are mechanically simpler. Mitigation is contractual—spare strategies, performance guarantees and rapid‑response service agreements.
How important is refrigerant choice in the comparison?
Very important. Low‑GWP refrigerants change compressor operating characteristics, charge volumes and safety/installation requirements. They can affect efficiency, maintenance needs and permitting timelines—factor refrigerant options into lifecycle models early.
Should I prioritize measured COP guarantees over nameplate EER/SEER numbers?
Yes. Nameplate or part‑load rated numbers are starting points. Require measured annual energy or COP guarantees under defined operating conditions and a clear acceptance test (seasonal or one‑year monitored verification) to lock in expected savings.
Do inverter centrals offer value for small or intermittent plants?
Less frequently. For very low‑hour or highly intermittent plants, the upfront premium is harder to recover. Modular screw banks or staged installations often win where runtime is limited or redundancy needs trump marginal efficiency gains.
What operational practices unlock the most savings for either platform?
Correct pump sequencing, tight delta‑T control, tower and condenser optimization, and active staging/dispatch based on real‑time electricity pricing and weather all realize the majority of potential savings. Digital commissioning and continuous FDD (fault detection and diagnostics) are high‑ROI measures regardless of compressor choice.
Final recommendation: update your procurement checklist to include measured performance guarantees, refrigerant strategy, grid value opportunities and clear service/SLA terms. With those elements in place, the compressor selection becomes a matter of operating profile and risk tolerance rather than marketing claims.